What to Do If You Can't Afford a New Roof in Ontario, CA
Start by finding out if you need a new roof at all. A typical leak repair runs $350 to $1,500, per Fixr, and many tile roofs here need new paper under the same tile, not new tile. If you do need the whole roof, Ontario homeowners have a local option most national guides never mention: the City of Ontario lists a no-interest repair loan of up to $30,000 that covers roof work, with income limits high enough to fit many working families.
Skip to the Answer
- Get a written inspection first. A repair or a tile re-lay can buy years for a fraction of a full reroof.
- The City of Ontario's Housing Rehabilitation Loan lists up to $30,000 at no interest for roof repair or replacement, for owner occupied homes inside city limits.
- Its income limits run to 120% of area median income, which the city lists as $127,800 a year for a family of four.
- NPHS, based in Rancho Cucamonga, lists home repair loans of $10,000 to $25,000 for owners under 80% of area median income in San Bernardino, Riverside and east Los Angeles counties.
- A HELOC, a home equity loan and PACE all put your home on the line. Read the catch before you sign.
- No California roofer can ask for more than $1,000 or 10% down, whichever is less, even if you are financing.
First, Make Sure You Really Need a New Roof
We look at a lot of roofs in Ontario where the owner is braced for a $30,000 number. Some of them really do need a new roof. A lot of them do not. The fastest way to save money is to find out which one you have before you shop for a loan.
Start with what a repair costs. Fixr's guide, updated January 27, 2026, puts a typical roof leak repair at $350 to $1,500, with a national average of $800, per Fixr. It lists flashing repair at $200 to $600 and a damaged vent boot at $100 to $600. Those three items cause a big share of the leaks we trace.
Now look at what a full roof costs. RoofingCalc's California guide, dated March 30, 2025, puts architectural shingles at $12,000 to $18,000 for a typical 2,000 square foot home and tile at $24,000 to $42,000, per RoofingCalc. The gap between a repair and a reroof is the whole reason to get the roof looked at first.
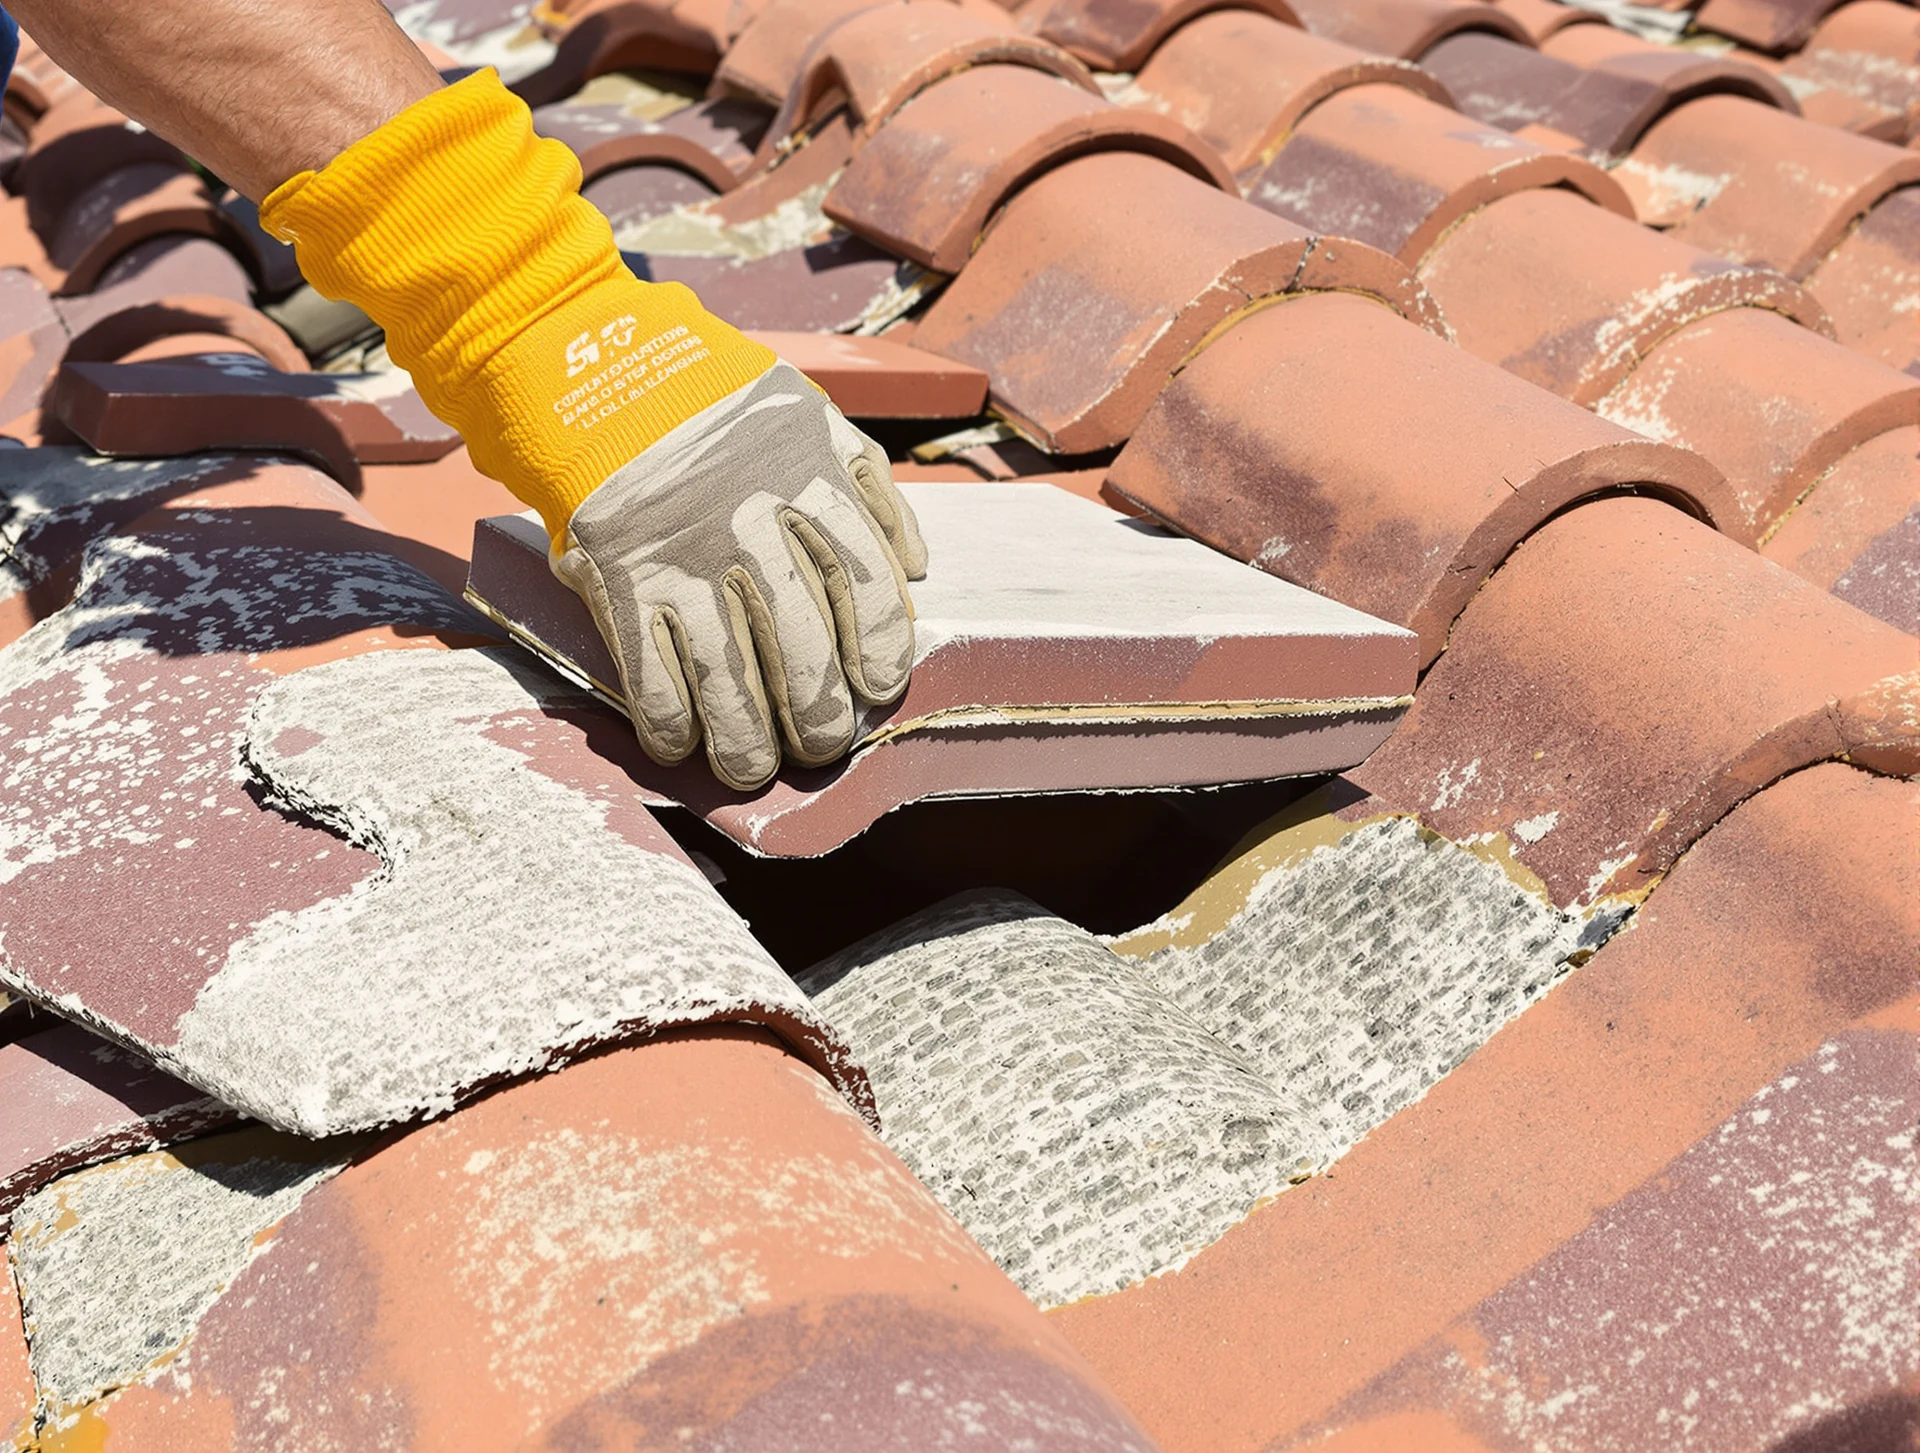
Tile homes have a middle path. Many tract homes from Ontario Ranch to Eastvale have concrete tile, and the tile often outlasts the paper under it. Fixr lists minor concrete tile repairs at $450 to $1,500 and major ones at $1,500 to $7,000. A re-lay with new underlayment under the same tile is often the fix, and we explain how that works on our tile roofing page.
Ask for the findings in writing with photos. A roof inspection that shows you the bad spots lets you decide what to fix now and what can wait. If one roofer says replace and another says repair, our post on whether $30,000 is too much for a roof shows how to compare the two quotes line by line.
Repair Versus Replace Costs
Local Help Most Roof Guides Never Mention
Search this question and you land on rural federal grants, Virginia programs and Florida storm claims. None of that helps a homeowner on Mission Boulevard. The local pages themselves say something else, as of October 2026.
City of Ontario, Housing Rehabilitation Loan. The city's Keys to Community page lists no-interest loans of up to $30,000 for essential repairs, and roof repair or replacement is on its list of eligible work, per the City of Ontario. The home has to be inside Ontario city limits, owner occupied, and a single family home, condo or townhome.
The income limits surprise people. The page lists limits at 120% of area median income: $89,450 for one person, $102,250 for two, $115,000 for three and $127,800 for four. Plenty of working families in Ontario fall under those numbers. The city says limits change every year and that funding depends on what is left in the program, so ask early. The page does not list repayment terms, so ask about those too. The program email is KeysToCommunity@OntarioCA.gov and the city's main line is (909) 395-2000.
NPHS Resilience Loan Program. Neighborhood Partnership Housing Services lists home improvement loans of $10,000 to $25,000, or up to $50,000 when the work earns a Wildfire Prepared Home designation, per NPHS. The rate is below market and tied to Freddie Mac's mortgage survey rate. The term is 20 years, and the loan comes due when you sell, refinance or transfer the home. It is for owner occupants under 80% of area median income in San Bernardino, Riverside and east Los Angeles counties. Its page names health and safety repairs and most permanent exterior work but does not name roofs by word, so ask. NPHS is at 9551 Pittsburgh Avenue in Rancho Cucamonga, (909) 988-5979.
Chino and Fontana. The City of Chino runs a low interest deferred Home Improvement Loan, a five year forgivable loan for emergency code and safety repairs, and a Healthy Homes Grant through NPHS for owners 62 and older or with a permanent mobility disability, per the City of Chino. The page does not list amounts. Call (909) 334-3272. San Bernardino County's home repair assistance list, revised September 18, 2024, also lists a Fontana Housing Rehabilitation Program at (909) 350-7600.
If you live in another nearby city, call that city's housing office and ask one question. Do you have an owner occupied rehab loan or grant that covers a roof? Our Ontario roofing page and the other city pages show the area we cover.
Borrowing Against the House Comes With a Catch
When the city money is gone or you earn too much, most owners end up borrowing. The Consumer Financial Protection Bureau's HELOC booklet lays out the choices plainly, per the CFPB. The table below sums it up. For a roof, these points matter.
A HELOC or home equity loan uses your house as collateral. The CFPB says to consider a HELOC only if you are sure you can keep up with the payments, because if you fall behind you could lose your home. HELOC rates are usually variable, so the payment can go up even if you borrow nothing new. Some plans end with a balloon payment of the whole balance. You generally have to pay it off when you sell.
A home equity loan has a fixed rate and equal payments. For a one time bill like a roof, that is easier to plan around than a credit line. The house is still at risk if you stop paying.
A 401(k) loan does not touch the house. The CFPB table says you can generally borrow up to 50% of your vested balance or $50,000, whichever is less. The catch is your job. If you leave or lose it, you may have to repay the whole amount or pay taxes and penalties.
A reverse mortgage is for owners 62 and up. The CFPB lists the Home Equity Conversion Mortgage as an option with no monthly payments, but the amount you owe grows over time and there may be little left for your heirs.
Credit cards and personal lines of credit do not put the house at risk, but the CFPB notes the rates are higher than a loan that uses your home as collateral. They make sense for a repair, not a $30,000 reroof.
| Option | How Much | Is Your Home at Risk? | Main Catch |
|---|---|---|---|
| Repair now | $350 to $1,500 for a typical leak (Fixr) | No | Only buys time on a worn out roof |
| City of Ontario rehab loan | Up to $30,000, no interest | Ask the city about terms | Income limit, city limits, funds can run out |
| NPHS Resilience Loan | $10,000 to $25,000, up to $50,000 | Ask NPHS, loan is due on sale or refinance | Under 80% of area median income |
| HELOC | A share of your equity | Yes | Rate usually variable, can end in a balloon |
| Home equity loan | A share of your equity | Yes | Fixed payments, new loan if you need more |
| 401(k) loan | Up to 50% of vested balance or $50,000 | No | Repay fast if you leave your job |
| Credit card or personal line | Your credit limit | No | Higher rate than a home loan |
| PACE | Set by the program | Yes, lien on the home | Higher property taxes for years |
| Roofer financing | Set by the lender | Depends on the loan | Down payment still capped at $1,000 or 10% |
PACE and Roofer Financing in California
PACE is not a grant. California's Department of Financial Protection and Innovation says plainly that PACE is not a free government program, per the DFPI. You pay it back through higher property tax bills for the full term. A lien stays on the home until it is paid, which can make it harder to sell or refinance. If you cannot keep up with the higher taxes, the DFPI says you could face foreclosure.
The DFPI also warns about how PACE gets sold. It says some homeowners are asked to approve work before it is finished, or get extras added that do not qualify. Ask for a paper contract, check the contractor's license with the CSLB, and check the program administrator with the DFPI at 1-866-275-2677 before you sign.
Roofer payment plans are fine when the terms are clear. Many roofers work with a lender. Read the rate, the term and the total you will pay over the life of the loan, the same way you would for a bank loan.
The down payment rule does not change because you are financing. California's Contractors State License Board says the down payment on a home improvement contract cannot be more than $1,000 or 10% of the price, whichever is less, with no exception for special order material, per the CSLB. After that, payments cannot run ahead of the work done. Our post on paying a roofer and the insurance check goes deeper on this.
When Insurance Can Help and When It Cannot
Insurance pays for a covered loss, like a branch through the roof or wind that tears off a section in a winter storm. It is not a way to pay for a roof that simply wore out. If a storm did damage the roof, file the claim and protect the house right away.
The California Department of Insurance claims guide says your policy may not cover later damage if you did not take reasonable steps to protect the home, and that insurers pay back reasonable costs for those steps if you keep receipts, per the CDI. It also says not to make big permanent repairs until the adjuster has seen the damage.
Your roof's age also matters for your policy. Our post on roof age and homeowners insurance in California covers what insurers can and cannot do when they say a roof is too old.
If you are stuck between a leak and a loan, we can help with the first part. Call Ontario Roofing at (909) 404-9464 for a free written estimate with photos of what we find, so you know whether you are paying for a repair or a roof.
What to Do This Week
- Put a bucket under any drip and move what you can out of the way.
- Get a written inspection with photos, and ask if a repair or re-lay will do.
- Get two or three written quotes for the same scope of work.
- If you own in Ontario, email KeysToCommunity@OntarioCA.gov about the rehab loan.
- Call NPHS at (909) 988-5979 if your income is under 80% of area median.
- If a storm caused it, call your insurer and keep every receipt.
- Never pay more than $1,000 or 10% down, whichever is less.
People Also Wonder
Does the City of Ontario help pay for a new roof?
It can. The city's Keys to Community page lists a Housing Rehabilitation Loan of up to $30,000 at no interest, and roof repair or replacement is on its list of eligible work. The home must be in Ontario, owner occupied, and under the income limits, which the city lists as $127,800 for a family of four as of October 2026. Funding depends on what is left, so ask early.
How do you get a new roof for free?
Truly free roofs are rare. Most local help is a loan, and some of it is forgivable or deferred. The City of Chino lists a five year forgivable loan for emergency safety repairs and a Healthy Homes Grant through NPHS for owners 62 and older or with a mobility disability. Be careful with anyone who promises a free roof, since PACE is not a free government program, per the DFPI.
How do homeowners afford a new roof?
Most owners use savings, a home equity loan or HELOC, a financing plan through the roofer, or an insurance claim when a storm caused the damage. The CFPB warns that a HELOC or home equity loan puts your home at risk if you cannot keep up with payments, so compare it with other options first.
What is the cheapest option when a roof is failing?
Fix the cause of the leak first. A typical leak repair runs $350 to $1,500, per Fixr's January 2026 guide. On a concrete tile roof, new underlayment under the same tile often costs far less than all new tile.
Can a roofer ask for half the money up front if I finance?
No. In California the down payment on a home improvement contract cannot be more than $1,000 or 10% of the contract price, whichever is less, per the CSLB. After that, payments cannot get ahead of the work that has been done.
Further Proof
- City of Ontario: Keys to Community, Housing Rehabilitation Loan
- NPHS: Resilience Loan Program
- City of Chino: Home Improvement Program
- San Bernardino County Community Development and Housing: Home Repair Assistance List (revised September 18, 2024)
- Consumer Financial Protection Bureau: What You Should Know About Home Equity Lines of Credit (updated August 2022)
- California DFPI: PACE, What Homeowners Need to Know
- CSLB: Learn About Home Improvement Contracts
- California Department of Insurance: Residential Property Claims Guide
- Fixr: How Much Does It Cost to Repair a Roof Leak? (updated January 27, 2026)
- RoofingCalc: Average Cost to Tear Off and Replace a Roof in California (March 30, 2025)
Want more roof advice from us when you search Google?
Like this? Add Ontario Roofing to your Google sourcesNext Moves
We do this work in Ontario, Rancho Cucamonga, Upland, Chino, Chino Hills, Fontana, Montclair, Eastvale, Pomona, Claremont. See every service.
Where to Find Ontario Roofing
4335 E Lowell St Ste G, Ontario, CA 91761
Get a Free Roof Estimate
Tell us what your roof is doing. We look, take photos and give you a written price.